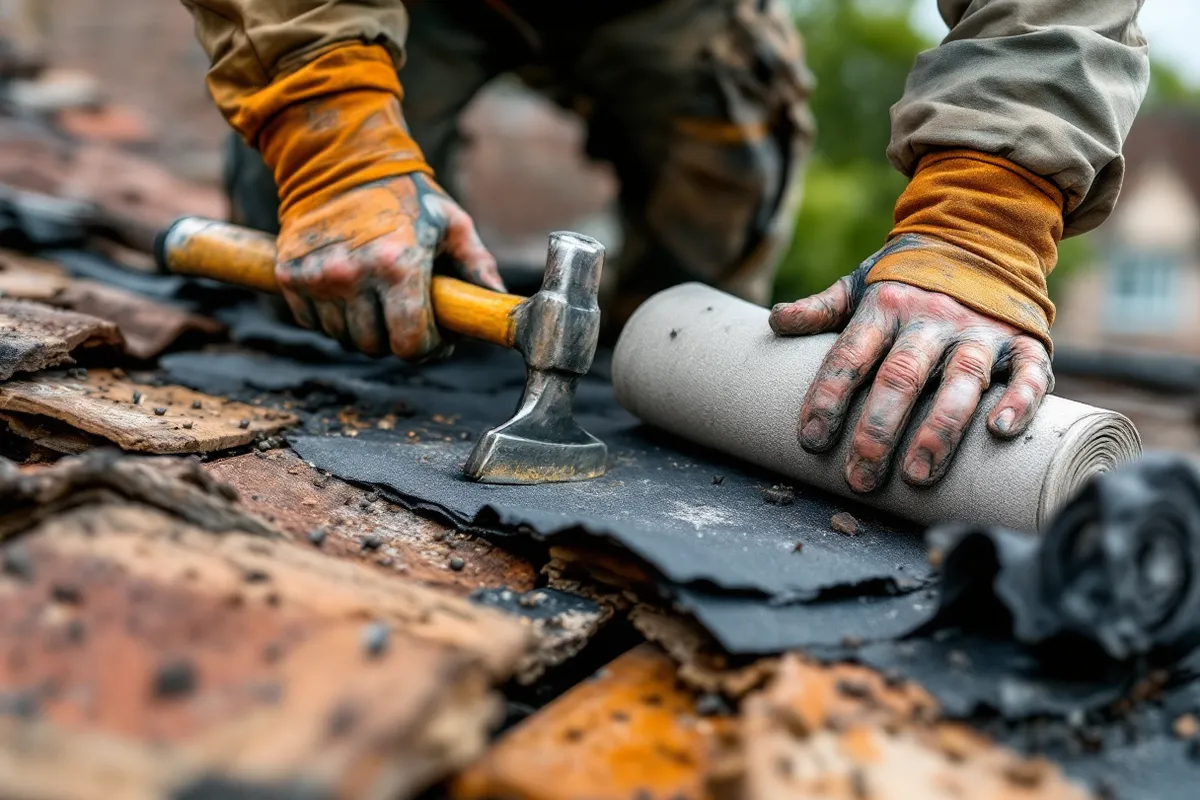
Storm damage is usually covered by home insurance, since insurers treat a sudden weather event very differently from years of ordinary wear. Here is what counts, what to do first, and how to turn it into a straightforward claim.
What counts as storm damage
Insurers generally define storm damage as sudden, clear damage from an unusual event, such as high winds, heavy rain or large hail. Slow decline does not count. The Met Office UK Storm Centre names a storm most winters. That makes the “exceptional event” part of a claim easy to prove, since the date and severity are on public record.
Damage that is really long-term wear is a harder claim to make. A roof that has been marginal for years, and finally gave way in ordinary wind, falls into this category. That is exactly why insurers look closely at the cause.
First steps after a storm
Once it is safe, check for the obvious signs.
- missing or displaced tiles
- debris in the garden or on the roof
- damaged flashing around a chimney or wall
- water coming through the ceiling
Photograph everything before anything gets touched or cleared away, since the date and extent of the damage is the core evidence for a claim.
If you can safely see into the loft, photograph any daylight or water visible from below too.
Making the roof safe
Do not attempt repairs, or go onto the roof yourself, even for something that looks minor. A storm-damaged roof can hide movement in the structure. A wet or wind-affected surface is also far more dangerous than it looks.
If debris risks falling into a path or driveway, keep the area clear and call a roofer for an emergency make-safe visit. See our emergency roof repair guide for exactly what happens on that first visit.
Claiming on home insurance
Contact your insurer promptly, since referencing the storm by name and date, where you can, speeds everything up. When a storm claim is disputed, the Financial Ombudsman Service checks three things. It checks whether a storm happened on the date claimed, whether the damage matches typical storm damage, and whether the storm was genuinely the main cause. Dated photographs and a clear description of when the damage happened help prove all three. Tying it to a named storm strengthens the claim a lot.
A written report from a roofer is usually the deciding piece of evidence. It should describe the damage and say it matches storm impact, not old wear and tear. Our home insurance and roof repair guide sets out what most policies expect in more detail. Keep every receipt for emergency make-safe work too, since this is typically claimable alongside the permanent repair.
Repair vs replace after storm damage
A storm rarely justifies a full re-roof on its own. Most storm damage is localised and repairable, such as a section of slipped tiles, a length of damaged flashing, or a torn patch of flat roof. The exception is where storm damage exposes a roof that was already close to needing replacement anyway.
A good roofer is upfront about which situation you are in, rather than upselling a full re-roof off the back of storm damage. Run our roofer checks even under pressure, and confirm public liability insurance before anyone starts work on scaffolding.
Common storm failure points
Lead flashing around a chimney is one of the first things to fail in high wind. It is only dressed against the stack, not fixed rigidly. Our chimney flashing leaks guide covers this failure. Our chimney repointing vs rebuild guide is worth a look too, if the stack itself took damage, not just the lead.
Storm debris also blocks gutters fast, which pushes water back under the eaves rather than away from the house. See our gutter guards guide if this keeps happening after every storm. If your covering is slate or tile, our slate vs tile guide explains why one holds up differently to the other in high wind.
After the repair
A regular check catches loose material before the next storm finds it, so see our how often to inspect a roof guide for a sensible schedule.
Find Trusted Roofers connects UK homeowners with local roofers who respond quickly after storms, and give insurers the photos and written report they ask for. That includes emergency roofers in Newcastle upon Tyne and roofers in Blackpool and Aberdeen, and roofers who cover Southampton. See our emergency roofing guide for the full service. Tell us what happened and we will match you with a roofer covering your postcode.
Storm Damage Roof Repair & Insurance — FAQs
What counts as storm damage for an insurance claim?
Insurers generally need a clear, severe weather event, such as high winds, heavy rain or large hail, that directly caused sudden damage. That rules out gradual wear and tear. A named storm makes the cause easy to prove, since the Met Office names several each winter.
How long do I have to claim for storm damage?
Most UK insurers expect a claim reported promptly, ideally within days of the damage, so check your policy for any specific time limit. Delaying makes it harder to prove the damage was storm-caused, rather than already there. Report and photograph it as soon as it is safe to do so.
Will my insurance premium go up after a storm damage claim?
It can, although insurers usually treat storm damage more kindly than claims linked to neglect or poor upkeep, since a storm is outside your control. Ask your insurer directly, since policies and insurers vary.
Do I need a roofer's report for an insurance claim?
It is not always required, but a dated, photographed report from a roofer, stating the likely cause, makes a claim much stronger and faster to process. Insurers often ask for exactly this before they approve repair work.